
 Facebook
 X
 Pinterest
 Copy Link
September was the month mortgage rates finally picked a direction, and it was not the one buyers were hoping for. The 30-year fixed rate climbed week after week to roughly 7.5 percent by month’s end, and mid-month the Federal Reserve raised its benchmark rate for the first time since July 2023. Here is what is important to understand as you read this month’s numbers: most homes that closed in September went under contract in August, when rates were closer to 6.7 percent. So September’s data is really a picture of August’s market. The full effect of higher rates will show up in October and November. What September does tell us is that, through another round of surprises, Denver’s market has kept a remarkably steady shape.
Market Overview – September 2026:
Median Sale Price: $575,000 — down 3.20% from August and down 1.88% from September 2025
New Listings: 4,887 — essentially flat from August (-0.06%) and down 1.51% from a year ago
Days in MLS (Median): 32 days — up from 27 days in August, but faster than the 35 days we saw last September
Close-Price-to-List-Price Ratio: 98.45% — nearly unchanged from August (98.53%) and slightly higher than last September (98.32%)
Current Conditions
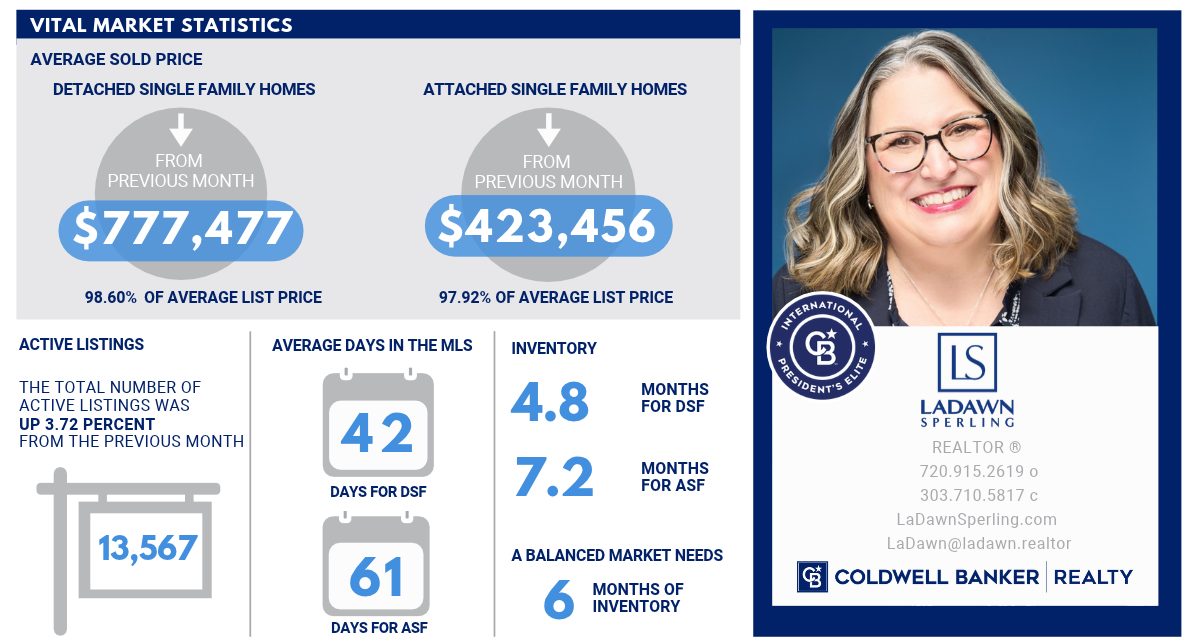
Inventory ended September at 13,567 active listings, the most we have seen in any September since 2011. That sounds like a lot, and it is more choice than buyers have had in years, but it is still about 10 percent below the historical September average for our area. The bigger story is on the sales side. Closings fell to 2,849, the fewest for any September in DMAR’s records going back to 2008, and year-to-date closings now trail 2025 by about 5 percent. Pending sales, our first real read on how buyers reacted to higher rates, slipped about 6 percent from August. That is a measured pullback, not a retreat.
Prices are where the steadiness shows. The month-to-month dip in the median reflects fewer closings in the middle and upper price ranges more than homes losing value. Zoom out and the year-to-date median is essentially unchanged from last year, and the year-to-date median for single-family homes sits at $650,000 for the third year in a row. Sellers who price well are still getting close to asking, at roughly 98.5 cents on the dollar. Buyers are cautious, and with Colorado’s job market softening a bit and rates higher, that caution makes sense.
With 4.76 months of inventory overall, we are in balanced territory, with more room to negotiate than buyers have had in a long time. That balance shifts depending on what you are buying. Condos and townhomes carry 7.21 months of supply, and their median price of $365,500 is down 6.28 percent from a year ago, which clearly favors buyers. At the other end, homes priced at $1 million and up are moving quickly, with a median of just 21 days in the MLS.
For Sellers
Price for the market you are selling into, not the one you remember. In the fourth quarter, the buyers still shopping are serious, but they are doing the math at 7 percent-plus rates. The sellers who do best right now build flexibility into their pricing from day one: room for a rate buydown or seller-paid concessions can matter more to a buyer than a lower list price. Presentation still counts. Take care of the roof, furnace and water heater questions before buyers ask them, and make the home feel ready for winter. If you are in a condo or townhome, price with HOA dues and insurance costs in mind, because buyers certainly will.
For Buyers
This fall may be one of the better windows we have seen in a while to buy with less competition. Inventory is at a multi-year high for this time of year, and as the holidays approach, many buyers step back to wait for a fresh start in January. Those who keep looking often find sellers more willing to talk. Today’s conversation is less about the rate itself and more about how you structure the purchase: rate buydowns, seller credits and adjustable-rate options are all on the table. Waiting for rates to fall is not a strategy. Knowing your real numbers is. Let’s look at yours together.
Looking Ahead
Over the next 30 to 60 days, I will be watching October and November closings closely, since that is where September’s rate climb will actually show up, and softer numbers would not be a surprise. Active listings usually taper through the fourth quarter as some sellers pull their homes for the holidays. What gives me confidence is the pattern: since 2023, year-to-date sales have stayed within about six percent of each other and prices within about three percent. Rates and policy keep surprising us, but this market has adapted every time.
Need Help Navigating This Market?
Whether you are thinking about a move this fall, planning for spring, or just trying to make sense of what higher rates mean for your next chapter, I would love to sit down and talk it through. A move is never just a transaction. It is a new job, a growing family, a downsize, a fresh start. Making good things happen for good people is what I do, and I am here whenever you are ready.
LaDawn Sperling, REALTOR®
Coldwell Banker Realty | West Denver Metro
📞 720.915.2619
📧 ladawn@ladawn.realtor
